The No. 1 maker of earth-moving equipment said retail sales of machinery jumped 49% in Jan., led by a 58% surge in N. America and a 56% increase in Latin America, as those regions started catching up to the recovery that began earlier in Asia. Caterpillar's (CAT) global engine sales rose 23% in Jan. Bucyrus, which is being bought by Cat, said Q4 EPS leapt 48% as sales nearly doubled, helped by an acquisition. Cat climbed 2.4% to 105.86.
Caterpillar Inc. manufactures and sells construction and mining equipment, diesel and natural gas engines, and industrial gas turbines worldwide. Its Machinery business engages in the design, manufacture, marketing, and sale of construction, mining, and forestry machinery, such as track and wheel tractors, track and wheel loaders, pipelayers, motor graders, wheel tractor-scrapers, track and wheel excavators, backhoe loaders, log skidders, log loaders, off-highway trucks, articulated trucks, paving products, skid steer loaders, underground mining equipment, tunnel boring equipment, and related parts.
This business also involves in the design, manufacture, remanufacture, maintenance, and service of rail-related products, as well as offers logistics services. The company's Engines business designs, manufactures, markets, and sells engines for electric power generation systems, locomotives, marine, petroleum, construction, industrial, agricultural, and other applications; and related parts. This business also provides remanufacturing services for other companies. Its Financial Products business provides various financing alternatives to customers and dealers for the company's machinery and engines, solar gas turbines, and other equipment and marine vessels, as well as offers loans to customers and dealers.
This business also provides various forms of insurance to customers and dealers to support the purchase and lease of its equipment. Caterpillar markets its products through distribution centers. The company was formerly known as Caterpillar Tractor Co. and changed its name to Caterpillar Inc. in 1986. Caterpillar was founded in 1925 and is headquartered in Peoria, Illinois.
Disclosure I am Long CAT shares.


Sunday, February 20, 2011

True To Form, Coke Raises Dividend 7% Streak Continues Since 1920 has paid Dividends
Coca-Cola (KO) has history that dates back to 1886. It also has a long record of returning cash to shareholders. It has paid dividends each year since 1920, about a year after it began listing on the New York Stock Exchange.
On Thursday, Coca-Cola's board approved lifting its quarterly shareholder payout by 7% to 47 cents a share. The beverage giant cited confidence in its long-term cash flow. This dividend is payable April 1 to shareholders of record as of March 15.
From an annual standpoint, Coca-Cola pays $1.88 a share for a current yield of about 3%. That's the biggest yield among the dividend paying stocks in IBD's Beverages-Non Alcoholic group. The company has raised its dividend for 49 consecutive years.
Coca-Cola is a member of the S&P 500 Dividend Aristocrats index, which is made up of blue-chip companies that have paid increasing dividends each year for at least 25 years. Coca-Cola is also one of billionaire investor Warren Buffett's biggest holdings in his Berkshire Hathaway (BRKA). As of Dec. 31, Berkshire Hathaway owned 200 million shares.
Meanwhile, Dr Pepper Snapple Group (DPS) popped Thursday after posting better-than-expected quarterly results. Thanks to increased demand for Dr Pepper, 7-Up and Sunkist beverages, the company reported Q4 earnings of 67 cents a share, up 52% and 3 cents above views. Sales grew 4% to $1.41 billion, also above views. Both top- and bottom-line growth was the best in years.
Looking ahead, Dr Pepper Snapple expects full-year 2011 profit of $2.70 to $2.80 a share. Analysts polled by Thomson Reuters expected $2.72 a share.
Dr Pepper Snapple Group came about in 2008 after it was spun off from Cadbury Schweppes Americas Beverages.
The company declared its first-ever quarterly dividend, of 15 cents a share, in November 2009. It most recently raised the payout by 67% to 25 cents a share in May.
Earlier this month, the company declared a quarterly dividend of a quarter a share. The annual $1-per- share rate works out to a yield of about 3%.
Disclosure NONE
On Thursday, Coca-Cola's board approved lifting its quarterly shareholder payout by 7% to 47 cents a share. The beverage giant cited confidence in its long-term cash flow. This dividend is payable April 1 to shareholders of record as of March 15.
From an annual standpoint, Coca-Cola pays $1.88 a share for a current yield of about 3%. That's the biggest yield among the dividend paying stocks in IBD's Beverages-Non Alcoholic group. The company has raised its dividend for 49 consecutive years.
Coca-Cola is a member of the S&P 500 Dividend Aristocrats index, which is made up of blue-chip companies that have paid increasing dividends each year for at least 25 years. Coca-Cola is also one of billionaire investor Warren Buffett's biggest holdings in his Berkshire Hathaway (BRKA). As of Dec. 31, Berkshire Hathaway owned 200 million shares.
Meanwhile, Dr Pepper Snapple Group (DPS) popped Thursday after posting better-than-expected quarterly results. Thanks to increased demand for Dr Pepper, 7-Up and Sunkist beverages, the company reported Q4 earnings of 67 cents a share, up 52% and 3 cents above views. Sales grew 4% to $1.41 billion, also above views. Both top- and bottom-line growth was the best in years.
Looking ahead, Dr Pepper Snapple expects full-year 2011 profit of $2.70 to $2.80 a share. Analysts polled by Thomson Reuters expected $2.72 a share.
Dr Pepper Snapple Group came about in 2008 after it was spun off from Cadbury Schweppes Americas Beverages.
The company declared its first-ever quarterly dividend, of 15 cents a share, in November 2009. It most recently raised the payout by 67% to 25 cents a share in May.
Earlier this month, the company declared a quarterly dividend of a quarter a share. The annual $1-per- share rate works out to a yield of about 3%.
Disclosure NONE
Closed-End Funds Can Open Profit Potential, funds for income, diversification
Most investors are familiar with mutual funds and exchange-traded funds (ETFs), but fewer are familiar with closed-end funds.
Despite being older than both mutual funds and ETFs, closed-end funds (CEFs) offer some distinct advantages for long-term investors who want to diversify their holdings.
Despite their name, CEFs are always open to new investors, even after the fund has started to trade. “Closed-end funds” derived that name because they offer a finite number of shares, so the amount of shares is limited or closed. As a result, a CEF does not continuously offer new shares. When a new investor wants to buy into the CEF, they will see a continuous bid and offer throughout the trading day based on the current market price of the CEF’s holdings. Since the CEF has a limited number of shares, its price is based on market demand.
In contrast, the price of a mutual fund is based on the net asset value (NAV) of its holding as determined at the end of the trading day. Another major difference between mutual funds and closed-end funds is that mutual funds can continuously offer new shares to new investors. In theory, a mutual fund can continuously grow to accommodate new investors. CEFs can not since they only offer a finite number of shares.
Aside from how their share price is determined, CEFs and mutual funds have many similar features: CEFs can invest in bonds, real estate, growth, small cap, value and international stocks. They also can use leverage, so some closed-end funds invest in real estate and other assets which require the use of borrowed money. Investors also buy into the CEF at par, so subsequent prices can go lower or higher.
Closed-end funds differ from exchange-traded funds because they provide active management, as opposed to the indexes that underlie ETFs.
One of the Oldest Fund Investments
There are about 750 CEFs offered, according to Brian M. Smith, director of the Closed-End Fund Association in Kansas City, Mo. Some of the oldest CEFs – General American Investors (NYSE: GAM), Adams Express Company (NYSE: ADX), Tri Continental (NYSE: TY) — started in 1929, Smith said. That was well before the introduction of mutual funds, which trace their origins to the Investment Company Act of 1940. CEFs also are more heavily regulated than mutual funds, Smith said, since they are registered both as corporations and mutual funds. Today, many of the same large companies that offer mutual funds — Royce Funds, Gabelli Funds, Nuveen , BlackRock — also use their investment expertise to offer CEFs.
Risks and Rewards of Closed-End Funds
CEFs are usually appropriate for people seeking income, and for investors “looking for the opportunity of greater return, who can also assume greater risk,” Smith said.
Since CEFs can invest in leveraged investments, such as non-liquid assets like a shopping center, and trade at a market value, they often trade at a discount, Smith explained. When this occurs, the average closed-end fund can be sold for less than the value of the assets it already owns. As the CEFs discount narrows, it creates greater returns for its investors.
Investors who purchase CEFs pay commissions which are no different than those in the mutual fund industry, Smith said. They can be bought at a discount from a broker-dealer, discount broker, financial adviser or as part of an auto-direct investment program,
Since CEFs can invest in leveraged assets, they are typically not offered in 401(k) plans, Smith said.
Disclosure I am long 18 closed end funds none of which are mentioned here.
My favorite Closed end fund research site is CEF CONNECT.
Despite being older than both mutual funds and ETFs, closed-end funds (CEFs) offer some distinct advantages for long-term investors who want to diversify their holdings.
Despite their name, CEFs are always open to new investors, even after the fund has started to trade. “Closed-end funds” derived that name because they offer a finite number of shares, so the amount of shares is limited or closed. As a result, a CEF does not continuously offer new shares. When a new investor wants to buy into the CEF, they will see a continuous bid and offer throughout the trading day based on the current market price of the CEF’s holdings. Since the CEF has a limited number of shares, its price is based on market demand.
In contrast, the price of a mutual fund is based on the net asset value (NAV) of its holding as determined at the end of the trading day. Another major difference between mutual funds and closed-end funds is that mutual funds can continuously offer new shares to new investors. In theory, a mutual fund can continuously grow to accommodate new investors. CEFs can not since they only offer a finite number of shares.
Aside from how their share price is determined, CEFs and mutual funds have many similar features: CEFs can invest in bonds, real estate, growth, small cap, value and international stocks. They also can use leverage, so some closed-end funds invest in real estate and other assets which require the use of borrowed money. Investors also buy into the CEF at par, so subsequent prices can go lower or higher.
Closed-end funds differ from exchange-traded funds because they provide active management, as opposed to the indexes that underlie ETFs.
One of the Oldest Fund Investments
There are about 750 CEFs offered, according to Brian M. Smith, director of the Closed-End Fund Association in Kansas City, Mo. Some of the oldest CEFs – General American Investors (NYSE: GAM), Adams Express Company (NYSE: ADX), Tri Continental (NYSE: TY) — started in 1929, Smith said. That was well before the introduction of mutual funds, which trace their origins to the Investment Company Act of 1940. CEFs also are more heavily regulated than mutual funds, Smith said, since they are registered both as corporations and mutual funds. Today, many of the same large companies that offer mutual funds — Royce Funds, Gabelli Funds, Nuveen , BlackRock — also use their investment expertise to offer CEFs.
Risks and Rewards of Closed-End Funds
CEFs are usually appropriate for people seeking income, and for investors “looking for the opportunity of greater return, who can also assume greater risk,” Smith said.
Since CEFs can invest in leveraged investments, such as non-liquid assets like a shopping center, and trade at a market value, they often trade at a discount, Smith explained. When this occurs, the average closed-end fund can be sold for less than the value of the assets it already owns. As the CEFs discount narrows, it creates greater returns for its investors.
Investors who purchase CEFs pay commissions which are no different than those in the mutual fund industry, Smith said. They can be bought at a discount from a broker-dealer, discount broker, financial adviser or as part of an auto-direct investment program,
Since CEFs can invest in leveraged assets, they are typically not offered in 401(k) plans, Smith said.
Disclosure I am long 18 closed end funds none of which are mentioned here.
My favorite Closed end fund research site is CEF CONNECT.
What Happens When You Over Contribute into IRAs?
You always hear that you need to “Save, Save, Save” for retirement, but is it really possible to save too much? When it comes to contributing to your IRA, it can.
Individual Retirement Accounts (IRAs) have annual contribution limitations that indicate how much you’re allowed to contribute. Anyone, regardless of income level can contribute to Traditional IRAs, but in addition to having a maximum contribution amount for a Roth IRA, you’ll also need to have annual income within limitations in order to contribute, at all.
It’s always best to prevent over contributions into IRAs, whether you have a Roth IRA or a Traditional IRA, so consult a tax professional if you have any questions about your allowed contribution amounts each year. If you do contribute more than you are supposed to, also consult a tax professional for advice on how to remove the overage to avoid penalties and tax implications.
Like a Roth IRA, you can contribute up to $5,000 per year, although if you earn less than $5,000 in a year you’re allowed to contibute 100% of your earned income (whichever is less). If you’re over the age of 50, you can make catch-up contributions of $1,000 for years 2009 and 2010.
Another time I see this occur is when someone has automatic contributions being directly deposited into their IRA. Either they forget the amount or just lose track of how much they’ve contributed (you should be always be able to check with your IRA custodian to see how much you’ve contributed). In the event that this occurs, you can always apply the excess contributions to a future tax year so as long as the amount does not exceed the contribution limit for next year, too. Keep in mind though that the 6% excess tax may still apply.
Disclosure I have a IRA at sharebuilder.com
Individual Retirement Accounts (IRAs) have annual contribution limitations that indicate how much you’re allowed to contribute. Anyone, regardless of income level can contribute to Traditional IRAs, but in addition to having a maximum contribution amount for a Roth IRA, you’ll also need to have annual income within limitations in order to contribute, at all.
It’s always best to prevent over contributions into IRAs, whether you have a Roth IRA or a Traditional IRA, so consult a tax professional if you have any questions about your allowed contribution amounts each year. If you do contribute more than you are supposed to, also consult a tax professional for advice on how to remove the overage to avoid penalties and tax implications.
Roth IRAs
For Roth IRAs, you can contribute $5,000 per year if you’re under the age of 50 and as much as $6,000 annually if you’re over the age of 50. The contribution limitation is adjusted based on your annual adjusted gross income, however. If you make between $105,000 and $120,000 a year as a single tax filer, you can make partial contributions based on the amount you earn. If you are married and make more than $166,000 but less than $176,000 you can also make partial contributions. If you make more than the stated annual income amounts, you’re not allowed to contribute to an IRA at all.What if You Contribute Too Much in a Roth IRA?
If you contribute more than you are allowed into a Roth IRA, you can withdraw the amount over the limit by the date you file your income tax return. If you fail to withdraw the amount you’ve over contributed, you will have to pay 6% excise tax on the overage amount (and any earnings it has made).Traditional IRA
Contributes to Traditional IRAs are tax deductible, and directly reduce the amount of taxable income you have in the year that you make your contributions.Like a Roth IRA, you can contribute up to $5,000 per year, although if you earn less than $5,000 in a year you’re allowed to contibute 100% of your earned income (whichever is less). If you’re over the age of 50, you can make catch-up contributions of $1,000 for years 2009 and 2010.
What if You Contribute Too Much in a Traditional IRA?
If you contribute more than you are allowed into a Traditional IRA, you can withdraw the excess contribution before you file your income taxes without penalty. If you don’t realize the over contribution until after you’ve filed your taxes, however, you will withdraw the excess amount and be penalized 6% for each year the money remained in your account when it should not have been there. You’ll need to file IRS Form 5329 when you withdraw your funds and it can be treated as an “early withdrawal”. Under Traditional IRA early withdrawal rules, you could be taxed twice on the withdrawal.How Does this Happen?
The most common time I see someone over contribute to an IRA (Roth or Tradtional) is when they have IRA’s at two different locations; for example, a bank at a brokerage firm. You have to understand that just because you have multiple IRA’s at different financial institutions doesn’t mean you can contribute $5,000 to each. That same rule applies to having both Traditional and Roth IRA’s.Another time I see this occur is when someone has automatic contributions being directly deposited into their IRA. Either they forget the amount or just lose track of how much they’ve contributed (you should be always be able to check with your IRA custodian to see how much you’ve contributed). In the event that this occurs, you can always apply the excess contributions to a future tax year so as long as the amount does not exceed the contribution limit for next year, too. Keep in mind though that the 6% excess tax may still apply.
Keep Track of How Much You Put Into Your IRA
It goes without saying that the easiest way to prevent putting too much into your Roth and Traditional IRA’s is to keep track of how much you’ve added. As I’ve mentioned before, even if you lose track, your IRA custodian should have a record of how much you’ve contributed for the current tax year.Disclosure I have a IRA at sharebuilder.com
Five High Yield Dividend Growth Stocks Raising Distributions
Dividend investors typically face a tradeoff between dividend yield and dividend growth. Companies with high yields often keep distributions unchanged or do not increase them at a rate that would compensate for the eroding power of inflation. Because of the higher yields, retirees tend to prefer the higher yield today. The companies with low yields on the other hand typically can afford to grow distributions much faster than the rate of inflation. Younger investors typically invest in these dividend growth stocks, in order to generate a sufficient yield on cost down the road.
The dividend growth companies that raised distributions last week were no exception:
Enterprise Products Partners L.P. (EPD) provides a range of services to producers and consumers of natural gas, natural gas liquids (NGLs), crude oil, refined products, and petrochemicals in the continental United States, Canada, and Gulf of Mexico. This master limited partnership announced a 1.30% increase in its quarterly distributions to 59 cents/unit. This was also a 5.40% increase over the Q1 2010 distribution. This dividend achiever has raised distributions every year since going public in 1998. Yield: 5.50
Plains All American Pipeline, L.P. (PAA), through its subsidiaries, engages in the transportation, storage, terminalling, and marketing of crude oil, refined products, and liquefied petroleum gas and other natural gas-related petroleum products (LPG) in the United States and Canada. This master limited partnership announced a 0.80% increase in its quarterly distributions to 95.75 cents/unit. This was also a 3.20% increase over the Q1 2010 distribution. This dividend achiever has raised distributions every year since going public in 1999. Yield: 5.90%
Genesis Energy, L.P. (GEL), together with its subsidiaries, operates in the midstream segment of the oil and gas industry in the Gulf Coast area of the United States. The company operates through four divisions: Pipeline Transportation, Refinery Services, Industrial Gases, and Supply and Logistics. This master limited partnership announced a 3.20% increase in its quarterly distributions to 40 cents/unit. This was also a 11.10% increase over the Q1 2010 distribution. In addition to that Genesis Energy announced the elimination of its incentive distribution rights to the general partner. This MLP has raised distributions for seven years in a row. Yield: 5.90%
Shaw Communications Inc. (SJR), a diversified communications company, provides broadband cable television, Internet, digital phone, telecommunications, and satellite direct-to-home (DTH) services primarily in Canada and the United States. The company increased monthly dividends by 5% to 7.67 canadian cents/share. Shaw Communications is a member of the international dividend achievers index, and has increased dividends for 9 years in a row. Yield: 4.40%
Alliant Energy Corporation (LNT) operates in electric and gas utility businesses in the United States. The company announced a 13% raise in its quarterly dividends to 42.50 cents/share. This was the ninth consecutive dividend increase for Alliant Energy. Yield: 4.50%
CVS Caremark Corporation (CVS) operates as a pharmacy services company in the United States. It operates in two segments, Pharmacy Services and Retail Pharmacy. The company announced a 43% raise in its quarterly dividends to 12.50 cents/share. This was the eight consecutive dividend increase for CVS Caremark. Yield: 1.40%
Most of the companies which raised distributions last week, and have raised distributions for over 5 years, were high dividend stocks such as master limited partnerships, utilities and telecoms. While their current yields are high, their dividend growth rates have been low. CVS on the other hand has a low current yield, however the dividend has been rising quickly. Just like anything in life, a balanced approach to include high yield stocks with low dividend growth, low yield stocks with high dividend growth and stocks with moderate yields and growth would ensure that investors receive a diversified income stream which provides sufficient current dividend income today, while also providing a decent dividend growth over time.
Full Disclosure: None
The dividend growth companies that raised distributions last week were no exception:
Enterprise Products Partners L.P. (EPD) provides a range of services to producers and consumers of natural gas, natural gas liquids (NGLs), crude oil, refined products, and petrochemicals in the continental United States, Canada, and Gulf of Mexico. This master limited partnership announced a 1.30% increase in its quarterly distributions to 59 cents/unit. This was also a 5.40% increase over the Q1 2010 distribution. This dividend achiever has raised distributions every year since going public in 1998. Yield: 5.50
Plains All American Pipeline, L.P. (PAA), through its subsidiaries, engages in the transportation, storage, terminalling, and marketing of crude oil, refined products, and liquefied petroleum gas and other natural gas-related petroleum products (LPG) in the United States and Canada. This master limited partnership announced a 0.80% increase in its quarterly distributions to 95.75 cents/unit. This was also a 3.20% increase over the Q1 2010 distribution. This dividend achiever has raised distributions every year since going public in 1999. Yield: 5.90%
Genesis Energy, L.P. (GEL), together with its subsidiaries, operates in the midstream segment of the oil and gas industry in the Gulf Coast area of the United States. The company operates through four divisions: Pipeline Transportation, Refinery Services, Industrial Gases, and Supply and Logistics. This master limited partnership announced a 3.20% increase in its quarterly distributions to 40 cents/unit. This was also a 11.10% increase over the Q1 2010 distribution. In addition to that Genesis Energy announced the elimination of its incentive distribution rights to the general partner. This MLP has raised distributions for seven years in a row. Yield: 5.90%
Shaw Communications Inc. (SJR), a diversified communications company, provides broadband cable television, Internet, digital phone, telecommunications, and satellite direct-to-home (DTH) services primarily in Canada and the United States. The company increased monthly dividends by 5% to 7.67 canadian cents/share. Shaw Communications is a member of the international dividend achievers index, and has increased dividends for 9 years in a row. Yield: 4.40%
Alliant Energy Corporation (LNT) operates in electric and gas utility businesses in the United States. The company announced a 13% raise in its quarterly dividends to 42.50 cents/share. This was the ninth consecutive dividend increase for Alliant Energy. Yield: 4.50%
CVS Caremark Corporation (CVS) operates as a pharmacy services company in the United States. It operates in two segments, Pharmacy Services and Retail Pharmacy. The company announced a 43% raise in its quarterly dividends to 12.50 cents/share. This was the eight consecutive dividend increase for CVS Caremark. Yield: 1.40%
Most of the companies which raised distributions last week, and have raised distributions for over 5 years, were high dividend stocks such as master limited partnerships, utilities and telecoms. While their current yields are high, their dividend growth rates have been low. CVS on the other hand has a low current yield, however the dividend has been rising quickly. Just like anything in life, a balanced approach to include high yield stocks with low dividend growth, low yield stocks with high dividend growth and stocks with moderate yields and growth would ensure that investors receive a diversified income stream which provides sufficient current dividend income today, while also providing a decent dividend growth over time.
Full Disclosure: None
Clorox: Why This Dividend Aristocrat Deserves More Respect
Popular brand names at Clorox (CLX) include: Clorox bleach, Green Works, Armor All, STP, Scoop Away cat litters, Kingsford, Hidden Valley, K C Masterpiece dressings and sauces, Brita, Glad bags and Burt’s Bees natural personal care products. 70% of the brands hold a #1 market share and another 18% hold a #2 market share position in their categories.
Fiscal 2010 segment results ($ figures in billions) were:

Dividends have been increased annually since 1977, easily qualifying CLX as an S&P 500 Dividend Aristocrat. Last May, the quarterly dividend was increased to 55¢ ($2.20 annualized).
Recent dividend history:

The markets were disappointed with fiscal Q1 results reported in November 2010, causing the low beta stock to drop $4 in 3 days. CLX said:
Leading household brands at CLX are growing at modest rates in the US and rapidly overseas. In the last 6 years, international sales have been growing 2-3 times the rate of domestic sales. 58% of international sales come from Latin America and only 5% are in Asia (offering large growth potential). International business is expected to account for a substantial portion of future growth
Company EPS guidance for FY2011 remains $4.05-$4.20. Fiscal Q2 results and any guidance updates will be released in the first week of February. Analysts are forecasting EPS of $4.00 in FY2011 and $4.48 for next year. Company finances remain strong, especially after selling the AutoCare businesses which will provide funds to repurchase over 12 million shares of treasury stock in FY2011.
In the last 6 years the stock has largely traded in the $55-65 range while dividends have been growing. At $65, with a P/E of 13X and a yield of 3.4% (the dividend will be raised in May), long term investors who can tolerate current conditions should find CLX an attractive investment.
Disclosure I am long CLX shares.
Fiscal 2010 segment results ($ figures in billions) were:
Dividends have been increased annually since 1977, easily qualifying CLX as an S&P 500 Dividend Aristocrat. Last May, the quarterly dividend was increased to 55¢ ($2.20 annualized).
Recent dividend history:
The markets were disappointed with fiscal Q1 results reported in November 2010, causing the low beta stock to drop $4 in 3 days. CLX said:
We faced a challenging economic environment, as evidenced by category softness in the U.S. along with the impact of the Venezuela currency devaluation," said Chairman Don Knauss. "Late first-quarter shipments were particularly soft and that trend has continued into the first weeks of our second quarter. While we're disappointed not to have delivered stronger first-quarter results, we manage our business for the long term. I believe we're taking the right actions to maintain the long-term health of our brands and help strengthen our categories as the economy recovers.Company guidance given for FY2011 was:
- 0-2% sales growth
- 25-50 basis points gross margin growth (unchanged)
- Diluted EPS from continuing operations in the range of $4.05-$4.20
While second quarter sales results are likely to be a little lower than previously anticipated, as reflected in our updated full year sales outlook, we believe our categories are stabilizing, giving us momentum into the second half of the year, and we should benefit from our recent market share gains. We have a solid new-product pipeline, enabling further growth across a number of categories, and we anticipate improved performance in the second half of the year, including topline growth in the range of 2 percent to 4 percent. Further, the impact of the prior-year Venezuela devaluation and unusually strong year-ago H1N1-related sales will be behind us.Q2 will have a goodwill impairment charge of $250-255 million ($1.78-1.82 diluted EPS) related to Burt's Bees business (with no tax benefit expected). In November 2010, CLX completed the sale of Auto Care businesses with an anticipated after-tax gain of $171 million. Including the $60 million deferred tax benefit in fiscal Q1, the gain on the sale is expected to be $231 million (reflected in discontinued operations).
Leading household brands at CLX are growing at modest rates in the US and rapidly overseas. In the last 6 years, international sales have been growing 2-3 times the rate of domestic sales. 58% of international sales come from Latin America and only 5% are in Asia (offering large growth potential). International business is expected to account for a substantial portion of future growth
Company EPS guidance for FY2011 remains $4.05-$4.20. Fiscal Q2 results and any guidance updates will be released in the first week of February. Analysts are forecasting EPS of $4.00 in FY2011 and $4.48 for next year. Company finances remain strong, especially after selling the AutoCare businesses which will provide funds to repurchase over 12 million shares of treasury stock in FY2011.
In the last 6 years the stock has largely traded in the $55-65 range while dividends have been growing. At $65, with a P/E of 13X and a yield of 3.4% (the dividend will be raised in May), long term investors who can tolerate current conditions should find CLX an attractive investment.
Disclosure I am long CLX shares.
Diana Shipping Shines Despite Shipping's Foggy Future
Diana Shipping (DSXdsx quote is in the business of dry bulk shipping. Diana ships dry bulk goods such as wheat, iron ore, coal, and other commodities. In the recent past, the dry bulk shipping industry has been beaten down. While the future of the dry bulk industry is hard to predict, Diana is positioned to do very well in the event that dry bulk shipping picks up again and I believe it can withstand a sluggish future in shipping.
Industry overview
The dry bulk shipping industry is driven by a variety of factors. The main factors (in order of importance) are:
1. Commodity Demand
2. Fleet Supply
3. Fuel prices
4. Weather
The volatility of these factors makes the dry bulk shipping a cyclical industry. The factors listed above led to a boom in 2007/2008. China's seemingly insatiable demand for dry bulk goods, particularly iron ore was the main driving factor. From late 2006 to late 2007, Diana's stock price returned 300%. However, as it turns out, China's demand was eventually satisfied and the industry went bust late in 2008. Subsequently, Diana's stock price fell about 60%.
The last couple years have been sluggish for shipping. What's worse is that shipping isn't out of the woods yet. There are more worries for the future of dry bulk shipping. This article from Morningstar gives a good overview of the industry. One would think that an industry whose forecast is fraught with fears would be an unattractive investment. I would argue otherwise. To quote Buffett, "Be fearful when others are greedy, greedy when others are fearful". The fear surrounding the shipping industry presents a great opportunity for investment.
As mentioned above, commodity prices have a large impact on the shipping industry. Below is a graph plotting the BDI (A measure of shipping prices) against the CRB index (a measure of commodity prices):
 From 2002-2009 there was a modest relationship between commodity prices and shipping rates. The rationale behind the relationship is as follows: As demand for commodities increases, the price increases. The buyers and sellers of the commodities need to transport the commodities to each other, thus demand for shipping increases subsequently raising shipping rates.
Starting in 2010, the relationship ceased to exist. Commodities and shipping started moving in opposite directions. A couple of reasons that prices may be staying low is because of an increasing supply of vessels, and the increasing price of crude oil. However, the high oil prices in 2007/08 didn't seem to slow down shipping rates. That being said, the only factor contributing to low shipping rates is the oversupply of vessels. I think this factor is overplayed. While vessel supply is expected to grow in the 10-12% range from 2009-2011, vessel scrapping is also on the rise. This will partially offset the increased supply in vessels. All things considered, I believe today's shipping prices are artificially low. Increasing commodity demand should increase shipping, leading to an increase in shipping rates.
Company overview
When people think bulk dry shipping, they think of shipping iron ore and coal. This is a major part of the industry, but does not contribute as much to Diana's bottom line as it does to its competitors. Based on Diana's fleet composition and major customers, it would appear that Diana is mainly focused on the supply of grain and wheat. Diana's fleet is comprised primarily of medium sized vessels. Medium and small sized vessels are used for shipping mainly iron ore, coal, and grains. A benefit of smaller ships is that they are the more economically efficient for transporting grains. The downside of medium-sized vessels (as compared to larger vessels) is that they don't benefit from the same economies of scale from transporting iron ore. Over the past few years, Diana's largest customers have been Cargill, BHP (BHP), The Australian Wheat board, and China National. These customers have represented approximately 35-50% of revenues. Based on these customers, it would appear that a sizable portion of Diana's revenue is derived from wheat.
In terms of commodities, Diana is more diversified than other shippers. This lowers the reliance on any one commodity and lowers the overall business risk. Based on the major competitors, it appears that a lot of Diana's business is coming from the Australian-China trade route. This could have a positive short-term impact on Diana, as Australia had an above average wheat harvest this year.
Diana shipping has been investing heavily in purchasing a new ships. Capital expenditures were ramped up in 2007/2008. Today, Diana has the youngest fleet in the industry. This is beneficial because newer ships benefit from improved fuel efficiency. In the face of rising oil prices, Diana will have a competitive advantage over its peers.
Revenue has seen inconsistent high growth. Diana's revenue has a 5-year average growth rate of 30.25%, including a large decrease in 2009. Operating income growth is a bit lower, but a similar story. Net income has been a bit more volatile. It showed slow growth prior to 2007, a large increase in 07/08, and has been back to '07 levels for the past two years. Inconsistent income is a bad sign, but a necessity of a highly cyclical industry.
Diana's financials are in good shape. Diana has a strong balance sheet, which is a must-have in a highly cyclical industry. The company's iquidity is the highest in the industry, and debt is the lowest. Because of a low level of leverage, Diana will benefit less in the boom cycle, but will fare better in a bust cycle. Considering a great deal of uncertainty in the future of dry bulk shipping, I think Diana Shipping is a safe bet.
Diana Shipping benefits from a strong management team. Management has been making decisions that are favorable for shareholders. The 5-year average ROA, ROE, and ROI metrics are 16.8%, 17.16%, and 20.86%, respectively. These are all well above the industry average, and very respectable numbers for any industry. Share purchases and buybacks are also in line with shareholders' interests. In 2007 Diana's stock price was trading in the $16.50-$42.50 range. During this time, management was aggressively selling its shares and using these proceeds to buy ships. It also paid nearly all of its net income through dividend payments. Management was rationally cashing in when the times were good, as if preparing for a slowdown. Well, that slowdown happened. After the booming shipping industry went bust in late 2008, Diana stopped selling stock, and stopped paying dividends.
In May 2010, management initiated a share buyback program for $100M, or 10% of its market capitalization. It would appear that management felt DSX stock price was undervalued in the $13-14 range. Today they are trading at $12.02. It is great to see a management team that has a track record of good decisions for shareholders. It is also a great to see management signaling to the market that DSX is undervalued by buying back shares. It would seem we both agree that DSX is undervalued.
Valuation
Diana is trading below its fair value. At a price of $12.02, it is trading at 7.92 P/E and 6.10 EV/EBITDA. These are average for the industry, and low by historical standards. During the boom of 2008, DSX was trading at double today's valuation multiples.
I ran a discounted cash flow analysis on DSX. Please click on the image below to view my assumptions/calculations;

My profit assumptions are in line with the cyclical nature of the business, aka: volatile swings in net income. Capital expenditure and depreciation assumption are based on the implications of recent capital expenditure. I obtain an intrinsic price of $18.29. The current market price is $12.02, offering a margin of safety equal to 34.28%.
Conclusion
The future of the dry bulk shipping industry is uncertain. What is certain, is that shipping is a cyclical industry, and has been suffering tremendously in the past couple years. Macroeconomic trends suggest that a recent surge in commodity prices should have increased shipping rates. This has not happened, and the dry bulk shipping industry stands to increase from catch-up in shipping rates to commodity prices. Diana Shipping has a diverse commodity shipping profile, with higher than average focus on grains.
In terms of financials, Diana Shipping has low leverage, and high profitability. Management has shown good performance through capital allocation decisions, impressive return on capital, and recent share buybacks. The stock price took a massive 60% tumble in late 2008 and while the rest of the market has recovered, it has stayed depressed. Today, Diana is an industry leader that is valued similarly amongst its competitors. By historical standards, it's trading at half of its valuation from its early 2008 highs. A discounted free cash flow analysis shows DSX exhibited a large margin of safety. An investment in Diana Shipping at $12.02 presents an opportunity of above industry average returns if dry bulk shipping remains grim, and great returns in the event of a turnaround in shipping.
Disclosure: I do not OWN DSX.
Industry overview
The dry bulk shipping industry is driven by a variety of factors. The main factors (in order of importance) are:
1. Commodity Demand
2. Fleet Supply
3. Fuel prices
4. Weather
The volatility of these factors makes the dry bulk shipping a cyclical industry. The factors listed above led to a boom in 2007/2008. China's seemingly insatiable demand for dry bulk goods, particularly iron ore was the main driving factor. From late 2006 to late 2007, Diana's stock price returned 300%. However, as it turns out, China's demand was eventually satisfied and the industry went bust late in 2008. Subsequently, Diana's stock price fell about 60%.
The last couple years have been sluggish for shipping. What's worse is that shipping isn't out of the woods yet. There are more worries for the future of dry bulk shipping. This article from Morningstar gives a good overview of the industry. One would think that an industry whose forecast is fraught with fears would be an unattractive investment. I would argue otherwise. To quote Buffett, "Be fearful when others are greedy, greedy when others are fearful". The fear surrounding the shipping industry presents a great opportunity for investment.
As mentioned above, commodity prices have a large impact on the shipping industry. Below is a graph plotting the BDI (A measure of shipping prices) against the CRB index (a measure of commodity prices):
[click to enlarge]
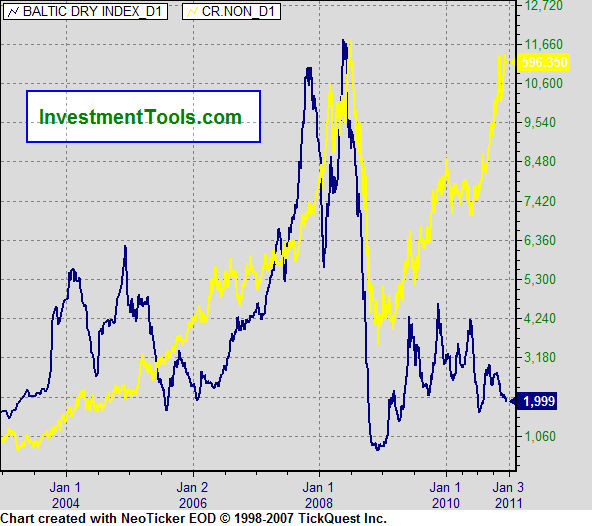
Starting in 2010, the relationship ceased to exist. Commodities and shipping started moving in opposite directions. A couple of reasons that prices may be staying low is because of an increasing supply of vessels, and the increasing price of crude oil. However, the high oil prices in 2007/08 didn't seem to slow down shipping rates. That being said, the only factor contributing to low shipping rates is the oversupply of vessels. I think this factor is overplayed. While vessel supply is expected to grow in the 10-12% range from 2009-2011, vessel scrapping is also on the rise. This will partially offset the increased supply in vessels. All things considered, I believe today's shipping prices are artificially low. Increasing commodity demand should increase shipping, leading to an increase in shipping rates.
Company overview
When people think bulk dry shipping, they think of shipping iron ore and coal. This is a major part of the industry, but does not contribute as much to Diana's bottom line as it does to its competitors. Based on Diana's fleet composition and major customers, it would appear that Diana is mainly focused on the supply of grain and wheat. Diana's fleet is comprised primarily of medium sized vessels. Medium and small sized vessels are used for shipping mainly iron ore, coal, and grains. A benefit of smaller ships is that they are the more economically efficient for transporting grains. The downside of medium-sized vessels (as compared to larger vessels) is that they don't benefit from the same economies of scale from transporting iron ore. Over the past few years, Diana's largest customers have been Cargill, BHP (BHP), The Australian Wheat board, and China National. These customers have represented approximately 35-50% of revenues. Based on these customers, it would appear that a sizable portion of Diana's revenue is derived from wheat.
In terms of commodities, Diana is more diversified than other shippers. This lowers the reliance on any one commodity and lowers the overall business risk. Based on the major competitors, it appears that a lot of Diana's business is coming from the Australian-China trade route. This could have a positive short-term impact on Diana, as Australia had an above average wheat harvest this year.
Diana shipping has been investing heavily in purchasing a new ships. Capital expenditures were ramped up in 2007/2008. Today, Diana has the youngest fleet in the industry. This is beneficial because newer ships benefit from improved fuel efficiency. In the face of rising oil prices, Diana will have a competitive advantage over its peers.
Revenue has seen inconsistent high growth. Diana's revenue has a 5-year average growth rate of 30.25%, including a large decrease in 2009. Operating income growth is a bit lower, but a similar story. Net income has been a bit more volatile. It showed slow growth prior to 2007, a large increase in 07/08, and has been back to '07 levels for the past two years. Inconsistent income is a bad sign, but a necessity of a highly cyclical industry.
Diana's financials are in good shape. Diana has a strong balance sheet, which is a must-have in a highly cyclical industry. The company's iquidity is the highest in the industry, and debt is the lowest. Because of a low level of leverage, Diana will benefit less in the boom cycle, but will fare better in a bust cycle. Considering a great deal of uncertainty in the future of dry bulk shipping, I think Diana Shipping is a safe bet.
Diana Shipping benefits from a strong management team. Management has been making decisions that are favorable for shareholders. The 5-year average ROA, ROE, and ROI metrics are 16.8%, 17.16%, and 20.86%, respectively. These are all well above the industry average, and very respectable numbers for any industry. Share purchases and buybacks are also in line with shareholders' interests. In 2007 Diana's stock price was trading in the $16.50-$42.50 range. During this time, management was aggressively selling its shares and using these proceeds to buy ships. It also paid nearly all of its net income through dividend payments. Management was rationally cashing in when the times were good, as if preparing for a slowdown. Well, that slowdown happened. After the booming shipping industry went bust in late 2008, Diana stopped selling stock, and stopped paying dividends.
In May 2010, management initiated a share buyback program for $100M, or 10% of its market capitalization. It would appear that management felt DSX stock price was undervalued in the $13-14 range. Today they are trading at $12.02. It is great to see a management team that has a track record of good decisions for shareholders. It is also a great to see management signaling to the market that DSX is undervalued by buying back shares. It would seem we both agree that DSX is undervalued.
Valuation
Diana is trading below its fair value. At a price of $12.02, it is trading at 7.92 P/E and 6.10 EV/EBITDA. These are average for the industry, and low by historical standards. During the boom of 2008, DSX was trading at double today's valuation multiples.
I ran a discounted cash flow analysis on DSX. Please click on the image below to view my assumptions/calculations;
[click to enlarge]
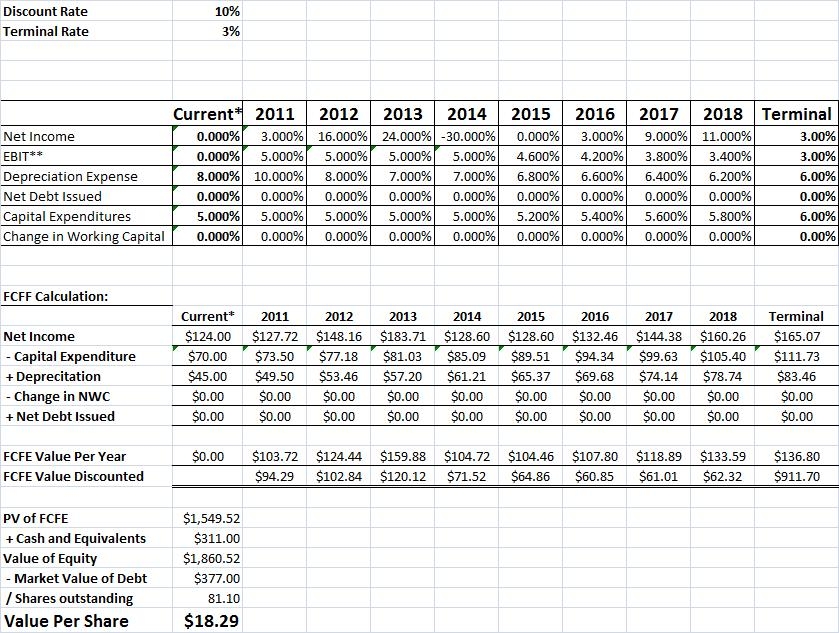
My profit assumptions are in line with the cyclical nature of the business, aka: volatile swings in net income. Capital expenditure and depreciation assumption are based on the implications of recent capital expenditure. I obtain an intrinsic price of $18.29. The current market price is $12.02, offering a margin of safety equal to 34.28%.
Conclusion
The future of the dry bulk shipping industry is uncertain. What is certain, is that shipping is a cyclical industry, and has been suffering tremendously in the past couple years. Macroeconomic trends suggest that a recent surge in commodity prices should have increased shipping rates. This has not happened, and the dry bulk shipping industry stands to increase from catch-up in shipping rates to commodity prices. Diana Shipping has a diverse commodity shipping profile, with higher than average focus on grains.
In terms of financials, Diana Shipping has low leverage, and high profitability. Management has shown good performance through capital allocation decisions, impressive return on capital, and recent share buybacks. The stock price took a massive 60% tumble in late 2008 and while the rest of the market has recovered, it has stayed depressed. Today, Diana is an industry leader that is valued similarly amongst its competitors. By historical standards, it's trading at half of its valuation from its early 2008 highs. A discounted free cash flow analysis shows DSX exhibited a large margin of safety. An investment in Diana Shipping at $12.02 presents an opportunity of above industry average returns if dry bulk shipping remains grim, and great returns in the event of a turnaround in shipping.
Disclosure: I do not OWN DSX.
DHT Maritime: A Value Play on Rising Rates
DHT Maritime (DHT) operates in the highly competitive crude oil shipping market. Their fleet consists of 3 very large crude carriers (VLCCs), 2 suezmax tankers, and 4 aframax tankers. In addition, the company recently bought a fourth VLCC (built in 1999) for $55mm.
I first became attracted to the company through this activist filing. Normally, I try to stay away from industries like this one; there is no competitive advantage or moat possible, rates are notoriously volatile, leverage ratios are high, etc. However, the filing laid out a great case for the stock to appreciate, noting it was materially undervalued compared to its peers. What really attracted to me to this, though, were the contracts they had signed for all of their ships, which had been locked into at or near the top of the market. These call for a mimimum base charter, and allow for DHT to capture around 1/3 of the prices above this base charter rate. With charter rates currently depressed, these contracts have proved to be a godsend for DHT, as they have enabled them to collect much more than they would if their ships were on the spot market.
What created the opportunity in this stock was historic mismanagement during the economic downturn. The company paid out all of their free cash flow (FCF) as a dividend until the beginning of 2008, when they set their dividend to a fixed rate of 25 cents per share. They continued to pay this dividend even as the stock market and economy cratered throughout 2008. They could do this because of the stability of cash flow from their chartered contracts. Then, in March 2009, the company raised equity for, in my mind, no good reason (the stated reason was to pay down debt, but the company wasn’t in violation of their covenants). The price they raised equity at implied a dividend yield of almost 25%, so why they raised equity instead of cutting the dividend and using those funds to pay debt I’ll never understand. Anyway, the new equity made the dividend unsustainable, and the company eventually had to cut their dividend due, in large part, to all of the new equity they raised (aren’t CEOs great?).
Flash forward to today. The company now has installed a new and seemingly talented management team. The company still has over a year left on all of their charter contracts (the first of the contracts don’t expire until April 2012, and could be renewed until as late as 2019). These contracts GUARANTEE the company will earn at least $40mm in FCF per year, which easily covers their new dividend payments of ~20mm annually.
The company trades for an EV of ~450mm and market cap of ~225mm. So an investor today gets a company with huge leverage and stable cash flows PLUS a call option on potentially rising tanker rates in the form of the profit sharing from the contracts and the newly purchased VLCC (which will go on the spot market).
The company also is kind enough to announce the appraised value of their fleet on their conference calls. With the recent purchase of the VLCC, the appraised value of the ships is just over $415mm. With EV at ~$440m, the investor is paying a premium of ~25m (around 5% of the value of their ships) as a premium for the cash flow guarantees and an option on rising tanker rates and prices.
So I think DHT is slightly undervalued at today’s prices. I can think of three types of people who would benefit from taking a harder look at DHT.
First, investors looking for a high dividend yield - DHT yields in excess of 8%, and the payout is well covered by the cash flows from the contracts. Second, investors who are looking for a way to pay a potential rise in tanker prices. DHT won’t benefit as much as its competitors who have their entire fleet completely on the spot market in such an environment, but they will benefit, and an investor doesn’t have to worry as much about the downside its competitors have in case rates collapse. Rising oil = Rising rates = rising tanker prices. The stressed capital markets + low rates have resulted in extremely depressed tanker prices, and as the global economy continues to recover tanker prices should continue to rise.
However, the main reason I wrote about this stock is for value investors. In the event that the market pulls back and takes DHT along with it, it could create an excellent value buying opportunity to pick the company up for below the value of their ships and earn the the contractually guaranteed cash flows for free.
Disclosure: I do not OWN DHT shares.
I first became attracted to the company through this activist filing. Normally, I try to stay away from industries like this one; there is no competitive advantage or moat possible, rates are notoriously volatile, leverage ratios are high, etc. However, the filing laid out a great case for the stock to appreciate, noting it was materially undervalued compared to its peers. What really attracted to me to this, though, were the contracts they had signed for all of their ships, which had been locked into at or near the top of the market. These call for a mimimum base charter, and allow for DHT to capture around 1/3 of the prices above this base charter rate. With charter rates currently depressed, these contracts have proved to be a godsend for DHT, as they have enabled them to collect much more than they would if their ships were on the spot market.
What created the opportunity in this stock was historic mismanagement during the economic downturn. The company paid out all of their free cash flow (FCF) as a dividend until the beginning of 2008, when they set their dividend to a fixed rate of 25 cents per share. They continued to pay this dividend even as the stock market and economy cratered throughout 2008. They could do this because of the stability of cash flow from their chartered contracts. Then, in March 2009, the company raised equity for, in my mind, no good reason (the stated reason was to pay down debt, but the company wasn’t in violation of their covenants). The price they raised equity at implied a dividend yield of almost 25%, so why they raised equity instead of cutting the dividend and using those funds to pay debt I’ll never understand. Anyway, the new equity made the dividend unsustainable, and the company eventually had to cut their dividend due, in large part, to all of the new equity they raised (aren’t CEOs great?).
Flash forward to today. The company now has installed a new and seemingly talented management team. The company still has over a year left on all of their charter contracts (the first of the contracts don’t expire until April 2012, and could be renewed until as late as 2019). These contracts GUARANTEE the company will earn at least $40mm in FCF per year, which easily covers their new dividend payments of ~20mm annually.
The company trades for an EV of ~450mm and market cap of ~225mm. So an investor today gets a company with huge leverage and stable cash flows PLUS a call option on potentially rising tanker rates in the form of the profit sharing from the contracts and the newly purchased VLCC (which will go on the spot market).
The company also is kind enough to announce the appraised value of their fleet on their conference calls. With the recent purchase of the VLCC, the appraised value of the ships is just over $415mm. With EV at ~$440m, the investor is paying a premium of ~25m (around 5% of the value of their ships) as a premium for the cash flow guarantees and an option on rising tanker rates and prices.
So I think DHT is slightly undervalued at today’s prices. I can think of three types of people who would benefit from taking a harder look at DHT.
First, investors looking for a high dividend yield - DHT yields in excess of 8%, and the payout is well covered by the cash flows from the contracts. Second, investors who are looking for a way to pay a potential rise in tanker prices. DHT won’t benefit as much as its competitors who have their entire fleet completely on the spot market in such an environment, but they will benefit, and an investor doesn’t have to worry as much about the downside its competitors have in case rates collapse. Rising oil = Rising rates = rising tanker prices. The stressed capital markets + low rates have resulted in extremely depressed tanker prices, and as the global economy continues to recover tanker prices should continue to rise.
However, the main reason I wrote about this stock is for value investors. In the event that the market pulls back and takes DHT along with it, it could create an excellent value buying opportunity to pick the company up for below the value of their ships and earn the the contractually guaranteed cash flows for free.
Disclosure: I do not OWN DHT shares.
Can Fixed Income ETFs Recapture Any Mojo?
At the end of August, every imaginable Fixed Income ETF had cracked the top half of the exchange-traded universe in relative strength percentile rank. Here on Thanksgiving Thursday, these same investments from the fixed income world have all dropped into the bottom half. In a “risk-on-risk-off” environment, few may find the change in momentum all that surprising. After all, stocks rocketed throughout the months of September and October; riskier assets have managed to hold onto those gains after three-and-a-half weeks in November. Yet even in November of 2010, where stocks have had their troubles, several different types of Bond ETFs have failed to act as “safe havens.” Consider the following examples:
1. International Bond ETFs and Emerging Market Bond ETFs. Fears of a sovereign nation failing to pay back its creditors have weighed heavily on international treasuries and international corporate bonds. Meanwhile, the US$ has bounced higher against the “euro” as well as emerging market currencies, creating some weakness in emerging bond offerings.
2. Muni Bond ETFs. You’d have to classify the recent mauling of state and national munis as bearish. Investors may be taking their cues from the bond crisis in the European Union. Is California next? Even though a massive wave of defaults inside of diversified baskets is improbable, the time spent waiting for bailouts may surpass shareholder pain thresholds.
3. High Yield Bond ETFs. In my estimation, high yield is just about where it should be on the relative strength rankings… higher than the rest of the fixed income offerings and a little lower than the S&P 500. Yet that doesn’t change the fact that 7- and 10-year yields have actually climbed since the QE2 announcement, while the long end of the treasury bond yield curve has surged. It follows that high yield bond ETFs are starting to see detractors.
For the time being, I am committed to diversified high yield. I also believe SPDR Convertible Bond (CWB) remains an attractive alternative to Treasury Bond ETFs.
Nevertheless, the higher intermediate and long-term investment grade yields climb, the greater the threat to credit spreads. The smaller the spread between investment grade and “junk,” the further out on the risk spectrum you may need to go. (That may not be a bad thing… as “aristocratic” dividend payers have phenomenal earnings yields.)
Disclosure I am long SPY, JNK, HYG, PHB, CWB, MUB and PCY.
1. International Bond ETFs and Emerging Market Bond ETFs. Fears of a sovereign nation failing to pay back its creditors have weighed heavily on international treasuries and international corporate bonds. Meanwhile, the US$ has bounced higher against the “euro” as well as emerging market currencies, creating some weakness in emerging bond offerings.
| Popular International Bond and Emerging Market Bond ETFs (10/25/10-11/24/10) | ||||||
| Approx % | ||||||
| SPDR Barclays International Treasury Bond (BWX) | -4.4% | |||||
| SPDR Barclay International Corporate Credit Bond (IBND) | -4.4% | |||||
| SPDR DB International Inflation Protected Bond (WIP) | -3.6% | |||||
| JP Morgan Emerging Market Bond (EMB) | -2.9% | |||||
| PowerShares Emerging Market Sovereign Debt (PCY) | -2.5% | |||||
| WisdomTree Emerging Market Local Debt (ELD) | -2.0% | |||||
| S&P 500 SPDR Trust (SPY) | 1.6% | |||||
| Popular State Muni Bond and National Muni Bond ETFs (10/25/10-11/24/10) | ||||||
| Approx % | ||||||
| SPDR Barclays California Muni (CXA) | -4.9% | |||||
| Market Vectors High Yield Muni (HYD) | -4.7% | |||||
| PowerShares Insured New York Muni (PZT) | -4.6% | |||||
| iShares S&P National Muni (MUB) | -3.9% | |||||
| SPDR Barclays National Muni (TFI) | -3.5% | |||||
| Market Vectors AMT Free Intermediate Muni (ITM) | -2.8% | |||||
| S&P 500 SPDR Trust (SPY) | 1.6% | |||||
| Popular High Yield Bond ETFs (10/25/10-11/24/10) | ||||||
| Approx % | ||||||
| SPDR Barclays High Yield Bond (JNK) | -1.0% | |||||
| iShares High Yield Corporate Bond (HYG) | -0.9% | |||||
| PowerShares High Yield Corporate (PHB) | -0.7% | |||||
| S&P 500 SPDR Trust (SPY) | 1.6% | |||||
Nevertheless, the higher intermediate and long-term investment grade yields climb, the greater the threat to credit spreads. The smaller the spread between investment grade and “junk,” the further out on the risk spectrum you may need to go. (That may not be a bad thing… as “aristocratic” dividend payers have phenomenal earnings yields.)
Disclosure I am long SPY, JNK, HYG, PHB, CWB, MUB and PCY.
Diversified Approach to Play Corporate Bond ETFs
As strength of a sustainable economic recovery continues to remain wary, unemployment remains high, and consumer demand grows at a snail’s pace, corporate bonds, and the exchange-traded funds (ETFs) that track them, could pose an opportunity for investors.
A notable play of the corporate bond market is the SPDR Barclays Capital International Corporate Bond ETF (IBND), which tracks the Barclays Capital Global Aggregate ex-USD > $1B: Corporate Bond Index, carries an expense ratio of 0.55%, and gives investors exposure to debt that's denominated in local currencies.
IBND focuses on investment-grade corporate bonds and gives exposure to the following currencies: Euro, Australian Dollar, Canadian Dollar, New Zealand Dollar, British Pound, Japanese Yen, Swiss Franc, Swedish Krona, and the Danish and Norwegian Krone. Although IBND excludes US Dollar-denominated bonds, it does include bonds issued by US companies, which are payable in other currencies. In fact, according to the fund’s prospectus, the US has the largest country weighting at 17.5%, followed by Germany at 16.1% and the United Kingdom at 12.5%.
In regards to sector weightings, IBND is heavily focused on financials, industrials, and utilities, which constitute 46.9%, 39.5%, and 11.6% of its asset base, respectively. Additionally, the underlying index that IBND seeks to track boasts a yield of 3.05%, which can be expected if IBND tracks its underlying index accurately.
Of the holdings in the newly traded ETF, all the bonds in the fund are rated Baa or higher, with nearly half of them carrying a rating of A or better. The average maturity for the bonds is 5.3 years with a modified duration of 4.4 years.
Another notable mention regarding the international bond market is that PowerShares has also filed the necessary paperwork to launch the International Corporate Bond Portfolio (PICB), which will seek to replicate the performance of the S&P International Corporate Bond Index and give exposure to international corporate bonds.
Another way to play corporate bonds is through the Vanguard Short-Term Corporate Bond Index Fund (VCSH). This ETF seeks to replicate the Barclays Capital US 1-5 Year Corporate Index, a benchmark that includes US dollar-denominated, investment-grade, fixed-rate, taxable securities issued by industrial, utility, and financial companies with maturities between one and five years
The majority of VCSH’s coupon rates lie between 4% and 6% and debt ratings of underlying holdings primarily lie between BBB and AA.
Although an opportunity may prevail in corporate bond ETFs, it's a good idea to have an exit strategy that helps mitigate the risks that they carry.
Disclosure I do not any of the above mentioned etfs I however have been watching IBND for a bit.
A notable play of the corporate bond market is the SPDR Barclays Capital International Corporate Bond ETF (IBND), which tracks the Barclays Capital Global Aggregate ex-USD > $1B: Corporate Bond Index, carries an expense ratio of 0.55%, and gives investors exposure to debt that's denominated in local currencies.
IBND focuses on investment-grade corporate bonds and gives exposure to the following currencies: Euro, Australian Dollar, Canadian Dollar, New Zealand Dollar, British Pound, Japanese Yen, Swiss Franc, Swedish Krona, and the Danish and Norwegian Krone. Although IBND excludes US Dollar-denominated bonds, it does include bonds issued by US companies, which are payable in other currencies. In fact, according to the fund’s prospectus, the US has the largest country weighting at 17.5%, followed by Germany at 16.1% and the United Kingdom at 12.5%.
In regards to sector weightings, IBND is heavily focused on financials, industrials, and utilities, which constitute 46.9%, 39.5%, and 11.6% of its asset base, respectively. Additionally, the underlying index that IBND seeks to track boasts a yield of 3.05%, which can be expected if IBND tracks its underlying index accurately.
Of the holdings in the newly traded ETF, all the bonds in the fund are rated Baa or higher, with nearly half of them carrying a rating of A or better. The average maturity for the bonds is 5.3 years with a modified duration of 4.4 years.
Another notable mention regarding the international bond market is that PowerShares has also filed the necessary paperwork to launch the International Corporate Bond Portfolio (PICB), which will seek to replicate the performance of the S&P International Corporate Bond Index and give exposure to international corporate bonds.
Another way to play corporate bonds is through the Vanguard Short-Term Corporate Bond Index Fund (VCSH). This ETF seeks to replicate the Barclays Capital US 1-5 Year Corporate Index, a benchmark that includes US dollar-denominated, investment-grade, fixed-rate, taxable securities issued by industrial, utility, and financial companies with maturities between one and five years
The majority of VCSH’s coupon rates lie between 4% and 6% and debt ratings of underlying holdings primarily lie between BBB and AA.
Although an opportunity may prevail in corporate bond ETFs, it's a good idea to have an exit strategy that helps mitigate the risks that they carry.
Disclosure I do not any of the above mentioned etfs I however have been watching IBND for a bit.
ETF to Watch: Treasury Ladder Fund (PLW)
The fixed income ETF space has grown considerably over the past two years, as investors worried about a slowdown in developed markets have bought up bonds despite record low yields. The first 11 months of 2010 saw cash inflows of approximately $100 billion into the ETF industry, and about $29 billion of that total went to bond products. The prices of bonds have skyrocketed in recent months on risk aversion, leading many analysts to worry a bond bubble is forming -- though these fears have somewhat calmed as equities have made a push to end 2010 on a positive note. Recent events have raised new concerns about the fixed income space, as Treasury prices fell and yields spiked to the highest level in quite some time.
From Monday to Wednesday, yields on the 10-year notes surged by 30 basis points, the largest two day run-up since the fall of the Lehman Brothers in 2008. But why the sudden spike in Treasury yields across the board, especially given ongoing worries in Europe? It seems that the general consensus is that the U.S. is not properly dealing with its budget deficit, with President Obama and the Congressional Republicans appear to be close to nearing an end to a tax-compromise deal that aims to jump-start consumer spending and growth, but at the same time increase the already massive deficit with the issuance of more debt.
This was further confirmed by a 10-year T-Bill auction that took place earlier in the week when the debt issuance failed to attract a solid number of investors. "It is extremely revealing of just how poor conditions are when we get one of the weakest 10-year auctions on record, even after the worst two day downdraft in 10-year yields since the turbulent, dark days of September 2008," said strategists at Nomura Securities. Focus will now shift to the long-term side of the market as the Treasury will issue 30-year bonds. Hopefully these notes will be better received than their shorter-term counterparts, but there is a fair amount of skepticism.
The 30-year auction will be closely followed today, putting all funds in the Treasury Bonds ETFdb Category in focus. In addition to dozens of funds honing in on various stretches of the maturity curve, there are a few ETFs that spread exposure throughout the Treasury market, including the PowerShares 1-30 Treasury Ladder Portfolio (NYSE: PLW). This fund follows the Ryan/Mergent 1-30 Year Treasury Laddered Index, which measures the potential returns of the U.S. Treasury yield curve based on approximately 30 equally weighted U.S. Treasury issues with fixed coupons, scheduled to mature in a proportional, annual laddered structure. If today's bond auction attracts a low level of demand, prices may take yet another hit, sending this fund down. But if the auction goes well and the recent sell-offs in Treasuries attract opportunistic buyers, the Treasury bond space could be due for a bounceback on Thursday.
Disclosure I am long PLW shares and have been for quite some time.
From Monday to Wednesday, yields on the 10-year notes surged by 30 basis points, the largest two day run-up since the fall of the Lehman Brothers in 2008. But why the sudden spike in Treasury yields across the board, especially given ongoing worries in Europe? It seems that the general consensus is that the U.S. is not properly dealing with its budget deficit, with President Obama and the Congressional Republicans appear to be close to nearing an end to a tax-compromise deal that aims to jump-start consumer spending and growth, but at the same time increase the already massive deficit with the issuance of more debt.
This was further confirmed by a 10-year T-Bill auction that took place earlier in the week when the debt issuance failed to attract a solid number of investors. "It is extremely revealing of just how poor conditions are when we get one of the weakest 10-year auctions on record, even after the worst two day downdraft in 10-year yields since the turbulent, dark days of September 2008," said strategists at Nomura Securities. Focus will now shift to the long-term side of the market as the Treasury will issue 30-year bonds. Hopefully these notes will be better received than their shorter-term counterparts, but there is a fair amount of skepticism.
The 30-year auction will be closely followed today, putting all funds in the Treasury Bonds ETFdb Category in focus. In addition to dozens of funds honing in on various stretches of the maturity curve, there are a few ETFs that spread exposure throughout the Treasury market, including the PowerShares 1-30 Treasury Ladder Portfolio (NYSE: PLW). This fund follows the Ryan/Mergent 1-30 Year Treasury Laddered Index, which measures the potential returns of the U.S. Treasury yield curve based on approximately 30 equally weighted U.S. Treasury issues with fixed coupons, scheduled to mature in a proportional, annual laddered structure. If today's bond auction attracts a low level of demand, prices may take yet another hit, sending this fund down. But if the auction goes well and the recent sell-offs in Treasuries attract opportunistic buyers, the Treasury bond space could be due for a bounceback on Thursday.
Disclosure I am long PLW shares and have been for quite some time.
Alerian MLP Index Concludes Stellar Decade
In the last decade (January 1, 2001 to December 31, 2010), the MLPs had one of the best gains ever for any industry group. Below are the beginning and ending values for the Alerian MLP Index along with the previous record reached in 2007.
The Alerian MLP Index, AMZ, almost tripled, very impressive considering how many quality companies had little or even negative appreciation in this decade. Dividend Aristocrats (with a minimum history of 25 years of annual increased dividends) such as General Electric (PFE) and Bank of America (BAC) reduced dividends during the recession, resulting in their removal from this elite group. AMZX, the comparable index including reinvested income, had a superb performance, rising more than five times the original value, with an equivalent compounded annual growth rate of more than 18%.
An alternative measure of performance is to begin with the record value reached in July 2007 (what turned out to signal the first wave of the financial market meltdown). The index is up 21 (6%) while the index including reinvested income rose 37% (equivalent to a compounded annual growth rate of 13%). Gold is one of only a few investments with higher growth rates since then.
The business model of MLPs has remained intact during the financial meltdown and recovery. Funds were raised to finance expansion of pipelines and other fixed assets while many companies had difficulty securing financing.
In 2009, a number of closed end funds and mutual funds were started to track MLP indices or concentrate on MLP investments. They give an averaging effect for the investor but do not have tax hassle (and lack tax benefits) associated with owning MLP units. AMJ is one of the oldest tracking funds (almost two years old). For AMJ, 10 shares approximate the value of AMZ with a current yield of almost 5%. Dividends are paid from distributions received net of fund expenses. There are a number of tracking funds but one, MLPL, needs to be singled out for its high risk. This fund's goal is to double the yield and capital appreciation (capital losses are also doubled). But added potential gains bring added risks. Doubler funds have poor records of tracking their base funds over the long term. In addition higher interest rates on borrowed funds, used to achieve doubler effects, will reduce net income for MLPL.
There are other ways to participate in MLP growth by purchasing shares in corporations. Kinder Morgan (KMR) and Enbridge Energy (EEQ) are stocks created by these MLPs. Shares track the comparable unit prices and pay stock dividends based on the distributions to the respective units, making them very tax efficient.
The rapid rise for MLPs in the last two years could cause them to run into headwinds in 2011. Higher values bring lower yields. The yield on the index has fallen to 6.2%, the lower region in its 15 year history. MLPs remain yield investments and low yields suggest topping in market prices. In the last two months the index was sluggish after reaching new record levels, while Treasury rates rose sharply (1 percentage point for the yield on the 10 year Treasury bond).
The long term outlook for the industry remains excellent, but it will be difficult to replicate the performance of the last decade. Growth rates could slow. Derived investment income from the index has risen at an annual rate of 5½% in the last three years which may be representative of the rate going forward, implying investment income of 38.50 in 2020. Today's low yield of 6.2% projects an ending value of 620 for the index, a 71% gain in this decade. Different assumptions will change the ending value, but it's logical to assume that the growth rate of income will slow for a more mature industry. Existing unit holders ought to be happy with this growth but new investors should be prepared for slower growth of distributions and higher yields which would further limit growth of unit prices (and the index).
Disclosure I am long GE, PFE and AMJ.
Date -- AMZ -- AMZX - Yield
12/31/00 - 131 - 191 - 8.8%
07/13/07 - 342 - 750 - 5.4%
12/31/10 - 363 - 1026 - 6.2%
12/31/00 - 131 - 191 - 8.8%
07/13/07 - 342 - 750 - 5.4%
12/31/10 - 363 - 1026 - 6.2%
An alternative measure of performance is to begin with the record value reached in July 2007 (what turned out to signal the first wave of the financial market meltdown). The index is up 21 (6%) while the index including reinvested income rose 37% (equivalent to a compounded annual growth rate of 13%). Gold is one of only a few investments with higher growth rates since then.
The business model of MLPs has remained intact during the financial meltdown and recovery. Funds were raised to finance expansion of pipelines and other fixed assets while many companies had difficulty securing financing.
In 2009, a number of closed end funds and mutual funds were started to track MLP indices or concentrate on MLP investments. They give an averaging effect for the investor but do not have tax hassle (and lack tax benefits) associated with owning MLP units. AMJ is one of the oldest tracking funds (almost two years old). For AMJ, 10 shares approximate the value of AMZ with a current yield of almost 5%. Dividends are paid from distributions received net of fund expenses. There are a number of tracking funds but one, MLPL, needs to be singled out for its high risk. This fund's goal is to double the yield and capital appreciation (capital losses are also doubled). But added potential gains bring added risks. Doubler funds have poor records of tracking their base funds over the long term. In addition higher interest rates on borrowed funds, used to achieve doubler effects, will reduce net income for MLPL.
There are other ways to participate in MLP growth by purchasing shares in corporations. Kinder Morgan (KMR) and Enbridge Energy (EEQ) are stocks created by these MLPs. Shares track the comparable unit prices and pay stock dividends based on the distributions to the respective units, making them very tax efficient.
The rapid rise for MLPs in the last two years could cause them to run into headwinds in 2011. Higher values bring lower yields. The yield on the index has fallen to 6.2%, the lower region in its 15 year history. MLPs remain yield investments and low yields suggest topping in market prices. In the last two months the index was sluggish after reaching new record levels, while Treasury rates rose sharply (1 percentage point for the yield on the 10 year Treasury bond).
The long term outlook for the industry remains excellent, but it will be difficult to replicate the performance of the last decade. Growth rates could slow. Derived investment income from the index has risen at an annual rate of 5½% in the last three years which may be representative of the rate going forward, implying investment income of 38.50 in 2020. Today's low yield of 6.2% projects an ending value of 620 for the index, a 71% gain in this decade. Different assumptions will change the ending value, but it's logical to assume that the growth rate of income will slow for a more mature industry. Existing unit holders ought to be happy with this growth but new investors should be prepared for slower growth of distributions and higher yields which would further limit growth of unit prices (and the index).
Disclosure I am long GE, PFE and AMJ.
Subscribe to:
Posts (Atom)